Lot No. LOT-6799 · offered October 18, 2026
Seeds, Crop Protection & FertilizerLot sheet
Fertilizer costs climb as supply chain bottlenecks tighten
Fertilizer prices moved higher again this week as Farm Progress reported supply chain disruptions pressuring nitrogen, phosphate and potash markets heading into the spring application window.
Market notes
- Fertilizer prices rose again this week according to Farm Progress reporting.
- Supply chain disruptions are pressuring nitrogen, phosphate and potash markets ahead of spring applications.
- Fertilizer accounts for roughly one-fifth of variable costs on Midwest grain farms, second only to seed.
- Spring prepay programs in Iowa, Illinois and Indiana are pricing higher than fall contracts based on early February negotiations.
- Retailers typically pass wholesale fertilizer cost increases through to farm-gate prices within one week.
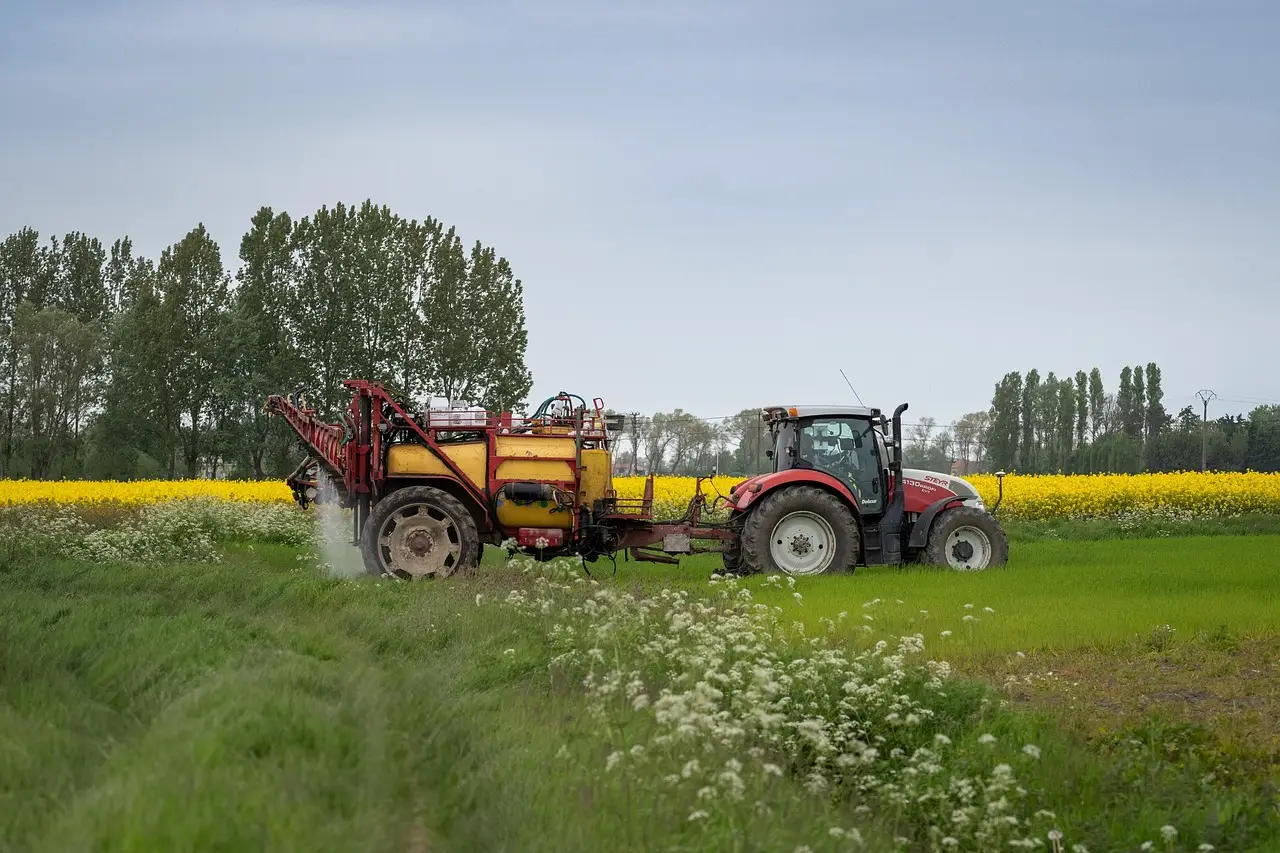
Fertilizer prices moved higher again this week as supply chain disruptions continue to pressure nitrogen, phosphate and potash markets, Farm Progress reported. The publication, which tracks input costs alongside commodity prices across U.S. farming regions, flagged the increase as carriers, producers and distributors grapple with overlapping logistics snags heading into the spring application window.
The latest move comes as growers finalize 2026 cropping plans and lock in spring nitrogen purchases. Retailers in the Midwest typically set prepay terms between January and mid-March, with delivery windows stretching through May. A supply-driven price spike at this stage of the calendar leaves operators choosing between paying up now, waiting and risking further increases, or trimming application rates — none of which pencil cleanly at current commodity bids.
Farm Progress did not detail a specific dollar figure in its headline coverage, but the trend matters because fertilizer typically ranks among the largest variable expenses for grain operations. Even modest price moves translate into margin pressure when scaled across thousands of acres, and retailers tend to pass wholesale increases through within a single week.
What's driving the supply chain pressure?
Three forces typically move fertilizer freight and pricing at once: barge and rail availability on the Mississippi and Illinois river systems, natural gas costs that feed urea and ammonia production, and overseas shipping disruptions that delay imports of phosphate rock and urea from North Africa and the Middle East. When all three pull in the same direction, retail prices follow fast.
Growers across the Corn Belt have watched nitrogen costs climb steadily over recent quarters as those levers pulled together. Potash and DAP followed similar paths, though with more regional variation. Whether the latest Farm Progress-flagged move extends that pattern or marks a sharper acceleration depends on how the supply chain resolves through March and April.
The practical question for operators: what does this change for the grower buying fertilizer next week? The honest answer is more money out and less flexibility in product choice. When wholesale moves sharply, retailers reprice within days, so a cost shift today typically shows up at the fill station before the week ends.
How tight is the margin squeeze?
Fertilizer routinely accounts for roughly one-fifth of variable costs on Midwest grain operations, second only to seed. Any sustained bump in nitrogen alone can erode projected per-acre margins at current corn and soybean cash bids, especially with new-crop revenue still hovering near or below the cost-of-production line on many farms.
Cooperatives across Iowa, Illinois and Indiana have begun signaling that spring prepay programs will price higher than fall contracts, based on early February negotiations between retailers and growers. That gives operators a narrow window to lock in tonnage before the next round of increases, if their working capital allows.
What should growers watch next?
Three indicators will tell operators whether the squeeze peaks soon or deepens:
- Barge freight rates on the lower Mississippi, which spike when Gulf export demand collides with domestic river shipping.
- Natural gas spot prices at Louisiana and Texas hubs, the single biggest variable cost for ammonia and urea production.
- Import arrival data from USDA's weekly export sales updates, which confirm whether phosphate and urea vessels are unloading on schedule.
If those signals ease by mid-March, retail prices should stabilize before side-dress applications begin. If they don't, growers should expect another round of increases before the May nitrogen push. Either path, the Farm Progress report confirms what retailers have been warning since late last year: input costs aren't cooperating with commodity revenue, and the bill lands at the plant.
via Google News: Fertilizer markets (Source)
More from Nathan Brooks
Show full bio
Staff writer covering regulation, policy and their impact on Agribusiness coverage for industry professionals at Agribusiness Wire.
483 articles